15 Sep
A fraud tool can block a criminal card test in milliseconds, but it can also reject a legitimate returning customer at the most valuable point in their journey. That is the real test behind any fraud scoring software review: not whether a platform detects risk, but whether it protects revenue without creating unnecessary checkout friction.
For merchants operating across markets, payment methods and acquiring relationships, fraud scoring must work as part of the wider payment stack. A score on its own is not a strategy. The value comes from how well the system uses transaction data, how clearly it supports operational decisions and how reliably it feeds the right transactions to the right payment route.
What fraud scoring software is designed to do
Fraud scoring software assigns a risk value to a payment attempt. It evaluates signals such as device characteristics, IP address, billing and delivery details, transaction velocity, customer history, issuer response patterns and behavioural anomalies. The higher the score, the more likely the transaction requires a challenge, manual review or decline.
The strongest platforms do not treat every unusual transaction as fraud. A high-value booking made from a new device may be entirely legitimate. Equally, a low-value transaction can be the first stage of card testing. Effective scoring looks at the relationship between signals, rather than relying on one rule such as a country mismatch or an unfamiliar email address.
This distinction matters particularly for travel, subscriptions, telecoms, gaming and other sectors where customer behaviour may not follow a simple retail pattern. Repeat billing, delayed fulfilment, cross-border card usage and rapid changes in spend can all be normal. A generic model can mistake these behaviours for risk unless it is configurable for the merchant’s business model.
Fraud scoring software review: the criteria that count
A useful review should start with commercial outcomes, not a feature checklist. Ask whether the software can lower fraud losses and chargebacks while maintaining approval rates and protecting legitimate customer conversions.
Decision quality, not just detection rates
A vendor may claim a high fraud detection rate, but that figure means little without its false-positive rate. Declining a fraudulent payment is beneficial. Declining a genuine customer can cost far more over time, especially where repeat purchases, subscriptions or high customer acquisition costs are involved.
Request performance data that separates prevented fraud, false positives, manual-review volume and chargeback outcomes. Where possible, assess results by payment method, region, product type and customer segment. A score that performs well for domestic card payments may require a different rule set for international transactions or alternative payment methods.
Also establish how the provider measures success. Chargebacks are a useful indicator, but they arrive after the transaction and can be influenced by fulfilment, customer service and descriptor clarity. Approval rate, authentication success and review turnaround should sit alongside chargeback data.
Rules, machine learning and merchant control
Modern fraud engines often combine rules with predictive models. This is usually the right approach. Machine learning can identify patterns that a team would not spot manually, while rules allow merchants to respond quickly to known threats, business exceptions and operational requirements.
The question is whether your team can understand and control the outcome. Can you set velocity limits for a card, device, email or IP address? Can you allow trusted customer cohorts, block known abusive signals and apply different thresholds for different markets? Can controls be adjusted without a lengthy development request?
Complete automation is not always the goal. For high-ticket orders or borderline scores, a manual-review queue may be commercially sensible. The platform should make that queue manageable by showing the evidence behind the score, rather than forcing analysts to assemble data from several systems.
Data coverage and signal quality
Fraud models are only as effective as the information they receive. Look for support for device intelligence, geolocation, payment history, account behaviour, transaction velocity and negative lists. The platform should also take account of payment-specific signals, including CVV and AVS results where applicable, 3D Secure v2 outcomes, issuer declines and token data.
More data is not automatically better. Data should be relevant, lawful and available at the right time in the payment flow. A scoring platform that requires fields your checkout does not collect may introduce friction or produce incomplete decisions. Confirm what data is captured through hosted payment fields, APIs and mobile SDKs before committing to a design.
Integration with payments and authentication
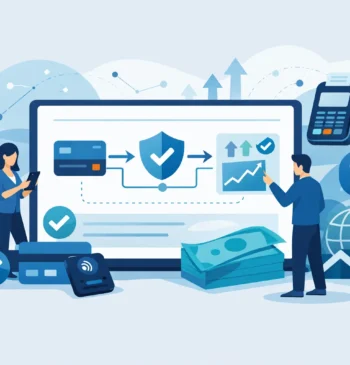
Fraud scoring is most effective when it can trigger action. A high-risk score may require a decline; a medium-risk score may be sent through 3D Secure; a low-risk score may proceed without added friction where the transaction and regulatory conditions allow.
Review how the solution connects with your gateway, payment orchestration layer, acquirers and CRM or order-management systems. API quality, webhooks, documentation and test environments matter because payment decisions must happen quickly and reliably. A technically impressive scoring engine that creates checkout delays or fails to return a clear decision will damage conversion.
Merchants using multiple acquirers should also examine whether risk data can inform routing. For example, a transaction may be acceptable for one acquiring route but require stronger authentication on another. This requires consistent data sharing and clear ownership of the final decision.
Reporting that supports action
Dashboards should help payment and risk teams answer practical questions: Which rules are generating the most declines? Where are chargebacks increasing? Is card testing concentrated in a particular channel? Are manual reviews preventing loss or simply delaying good customers?
Look for transaction-level audit trails and reporting that can be filtered by market, payment method, issuer response, score band and decision. The ability to export data and connect it to business intelligence tools is valuable for larger teams. For smaller teams, clear alerts and concise reporting may be more useful than a complex analytics suite.
Where fraud scoring software can fall short
No score can resolve every payment risk. Friendly fraud, for example, may involve a legitimate cardholder disputing a purchase after receiving goods or services. Fraud scoring can reduce exposure by identifying unusual behaviour, but compelling evidence, clear customer communications and chargeback management remain essential.
Scoring can also create a false sense of security if it is not reviewed. Fraudsters adapt quickly to predictable thresholds, stolen identities and synthetic profiles. A rule set that worked six months ago may now be allowing card testing through or wrongly declining a valuable audience.
Privacy and governance require equal attention. Merchants need clarity on where data is processed, how long it is retained, which parties can access it and how automated decisions are explained. For businesses serving European customers, the design should support data protection obligations without weakening the controls required to prevent fraud.
A practical evaluation process
Before selecting a provider, map your current payment risks. Include chargeback reason codes, decline patterns, fraud types, customer geographies, payment methods and peak trading periods. This prevents a review from becoming an abstract comparison of features.
Then test the proposed configuration against real scenarios. Include card testing, account takeover, first-time high-value purchases, repeat subscription payments, cross-border customers and known good buyers using new devices. Ask how each scenario would be scored, what action would follow and whether the decision can be changed by a merchant rule.
A structured assessment should cover four areas:
- Decision performance, including fraud capture, false positives and approval-rate impact.
- Operational control, including rules, case management, alerts and audit trails.
- Technical fit, including APIs, webhooks, latency, data availability and payment-flow compatibility.
- Commercial fit, including pricing, implementation effort, support quality and the cost of additional review work.
Run a monitored pilot where possible. Baseline fraud, chargeback and conversion metrics before launch, then compare results by channel and customer segment. Avoid judging a platform solely on its first weeks of performance, as models and rules often need tuning once they meet live traffic.
Choosing the right operating model
Some merchants need a standalone specialist tool with advanced investigation features. Others benefit more from fraud controls built into their payment gateway or orchestration layer, where scores can directly influence authentication, routing and transaction handling. Neither approach is inherently better.
The right choice depends on transaction volume, internal risk expertise, market coverage and payment complexity. A growing merchant may prioritise quick integration and managed support. A high-volume business with several acquiring partners may need granular control, custom data feeds and a team that can continuously optimise strategies.
AllSecure approaches fraud prevention as a payment-performance function, combining configurable controls with the payment infrastructure needed to act on them. That matters when the objective is not simply to stop suspicious transactions, but to accept more legitimate payments safely across channels and territories.
Choose fraud scoring software that gives your team clear decisions, useful control and evidence of commercial impact. The right system should make risk management quieter in the background while legitimate customers complete payment with confidence.
Related Articles