25 Oct
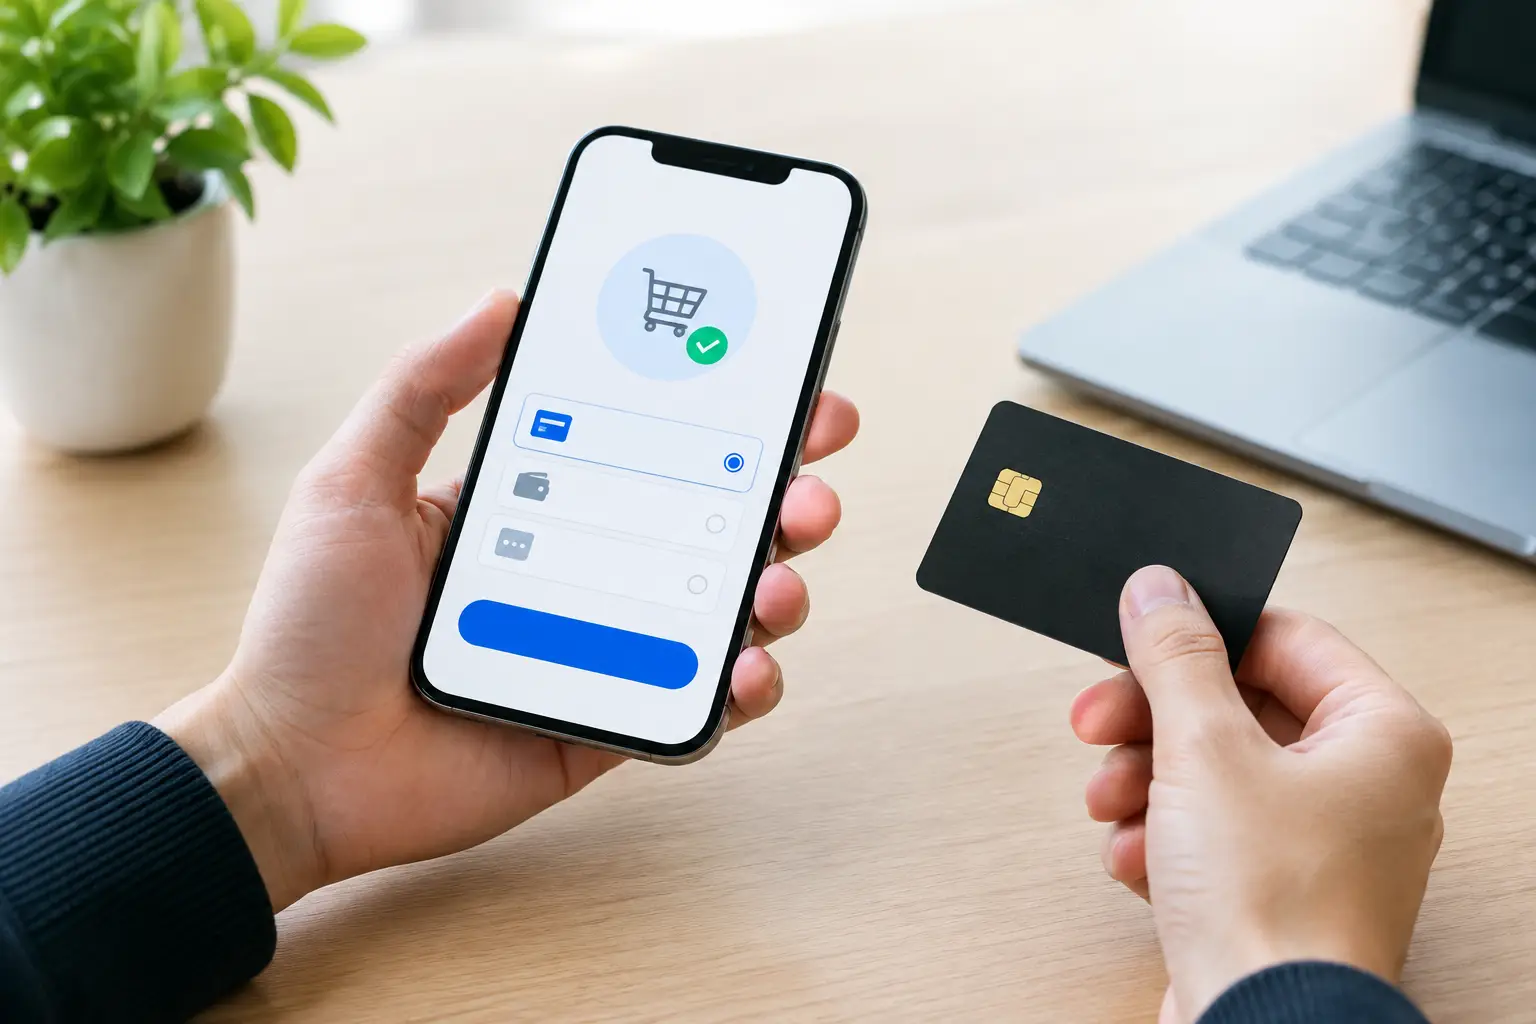
A mobile checkout has seconds to earn trust. If a card field feels awkward, a wallet is missing, or an authentication step fails to return the customer to the app, revenue is lost before the payment team can investigate it. The best mobile checkout SDKs reduce this friction while giving merchants enough control over security, routing and payment method availability.
For growing e-commerce businesses, the right choice is not simply the SDK with the quickest demo. It is the one that fits your acquiring setup, target markets, risk profile and checkout design. This matters especially for subscription, travel, telecoms and regulated sectors, where recurring billing, stronger authentication and chargeback controls must work together.
What a mobile checkout SDK should do
A mobile software development kit gives iOS and Android teams pre-built payment components and secure methods for collecting card or wallet credentials. Rather than handling raw card data inside the app, the SDK tokenises payment information and passes it to the payment platform for authorisation.
That reduces integration effort and can substantially limit the application’s exposure to sensitive card data. It does not remove the merchant’s broader compliance responsibilities, but it supports a more controlled PCI DSS approach when implemented correctly.
A credible SDK should cover the payment moment as well as the exceptions around it. That includes Apple Pay and Google Pay, saved credentials, 3D Secure v2 authentication, clear failure states, localisation and webhooks or server-side events that keep the app and back office aligned. For businesses accepting payments internationally, multi-currency presentation and locally relevant payment methods are equally commercial requirements.
The critical distinction is between an attractive payment form and a complete payment operation. An SDK can collect a card correctly but still be the wrong choice if it cannot work with your preferred acquirer, support intelligent transaction routing or provide the data needed to manage disputes.
The best mobile checkout SDKs to consider
There is no universal winner. The best mobile checkout SDKs differ in how much control they provide, which payment ecosystem they prioritise and how well they fit complex acquiring arrangements.
Stripe Payment Sheet
Stripe’s native payment components are widely used by product teams that want a quick route to cards, wallets and saved payment methods. Payment Sheet offers a maintained checkout interface for iOS and Android, reducing the amount of UI that developers need to build and test.
It is a strong fit for merchants who operate comfortably within Stripe’s processing model and want fast implementation for standard e-commerce or subscription use cases. Its trade-off is strategic: merchants with multiple acquirers, high-risk acceptance needs or country-specific routing requirements may need more flexibility than a single-processor approach provides.
Adyen Drop-in and Components
Adyen provides mobile Drop-in interfaces and Components that offer a choice between pre-built checkout and deeper UI customisation. The platform is often considered by larger international businesses that need cards, digital wallets and a range of local payment methods under one commercial arrangement.
Its strength lies in global payment coverage and enterprise operating capability. It can be well suited to merchants with the resources to configure and manage a more detailed payment programme. Smaller teams should assess implementation effort, commercial terms and whether the platform’s acquiring model matches their markets and category.
Braintree Mobile SDK
Braintree’s SDK remains a recognised option for businesses that value PayPal alongside card acceptance and digital wallets. It supports native mobile integrations and can be practical where the customer base already expects PayPal as a checkout option.
The decision should go beyond wallet availability. Check the payment methods available in every launch market, how recurring payments are handled, and whether the risk controls and processor setup support your business model. A familiar brand at checkout can help conversion, but only if approval rates and operational support remain dependable.
Worldpay mobile integration options
Worldpay offers mobile payment integration capabilities that can appeal to established merchants seeking card acquiring support at scale. Its proposition is typically strongest where enterprise payment operations, existing acquiring relationships and broader commerce infrastructure are part of the buying decision.
Teams should validate the precise SDK and API capabilities for their region, operating system and checkout architecture. Enterprise platforms often provide extensive functionality, but the implementation journey may be less lightweight than a developer-first solution. That may be acceptable when resilience, acquiring access and operational governance are the priority.
A gateway-led, acquirer-flexible SDK approach
For merchants that need more than one processor, the most effective option may be a gateway-led checkout integration rather than a processor-specific SDK. This approach separates the mobile checkout layer from the acquiring strategy, allowing payment teams to connect different PSPs, acquirers and alternative payment methods behind a consistent customer experience.
It is particularly relevant for businesses expanding across Europe and further afield, or operating in verticals where acquiring coverage can change by market, product or risk appetite. A platform such as AllSecure can support this model through configurable payment flows, tokenisation, 3D Secure v2 and access to multiple payment providers. The value is not merely technical choice: it gives payment teams room to protect approvals when a single acquiring route is no longer enough.
Assess the SDK against your payment flow
A useful evaluation starts with real customer journeys, not a generic feature checklist. Map a first-time card payment, wallet payment, saved-card purchase, failed authentication, refund and subscription renewal. Then ask how the SDK, gateway and acquirer behave at each stage.
Pay close attention to 3D Secure. The app must handle challenge flows without confusing the customer or losing the transaction state when they return from an issuer authentication screen. Frictionless authentication is preferable where permitted, but the payment setup must also manage challenges reliably when they are required.
Token handling deserves the same scrutiny. Network tokenisation can improve security and support better authorisation performance, while gateway tokens can make it easier to run recurring billing and change acquirers without asking customers to enter their card details again. The exact portability of tokens varies, so confirm what happens if you add a new processor or move volume between routes.
For subscriptions, check whether the SDK supports the initial customer consent flow while your back end correctly stores the mandate and transaction indicators needed for later merchant-initiated payments. A polished first purchase does not solve failed renewals, involuntary churn or the need to update expired credentials.
Security and compliance cannot be bolted on later
Mobile payment security is an architecture decision. Use provider-hosted fields or approved native components so card data is handled within the payment provider’s controlled environment. Keep secret keys and transaction logic on your server, not embedded in the application, and verify server-side payment status before delivering goods or activating a service.
Fraud controls should also be configurable by market and transaction type. Device signals, velocity rules, IP and BIN checks, 3D Secure policies and manual review queues can each help, but over-aggressive rules can suppress good customers. The right target is not the lowest possible fraud rate in isolation. It is a commercially sound balance of approvals, fraud loss, chargebacks and customer experience.
For high-risk merchants, confirm acceptance and acquiring eligibility before committing development resource. An SDK cannot compensate for a processor that will not support the category, markets or transaction profile you need. Early alignment between product, finance, compliance and payment operations prevents expensive rework.
Build for observability, not just launch day
A checkout is only as dependable as the visibility behind it. Your implementation should send enough data to identify where customers abandon: payment method selection, card entry, wallet authorisation, 3D Secure challenge or issuer decline. Separate technical failures from bank declines and authentication failures, otherwise teams may fix the wrong problem.
Monitor approval rates by acquirer, issuer country, card scheme, payment method and app version. If performance drops following an app release or an acquirer configuration change, the payment team needs evidence quickly. Webhooks, transaction search, real-time alerts and reconciliation data turn the SDK from a front-end convenience into an operational payment capability.
Choose the SDK around the payment strategy
A fast native integration is valuable, but it should not lock the business into weak acquiring coverage, limited payment methods or an inflexible fraud model. Select the mobile checkout SDK that gives customers the shortest credible path to pay and gives your team the control to improve that path as markets, issuers and risk conditions change.
The strongest mobile checkout is rarely the one with the most features on paper. It is the one that keeps paying customers moving, gives declined customers an appropriate alternative, and leaves your business ready to adapt when growth creates new payment demands.
Related Articles