22 Sep
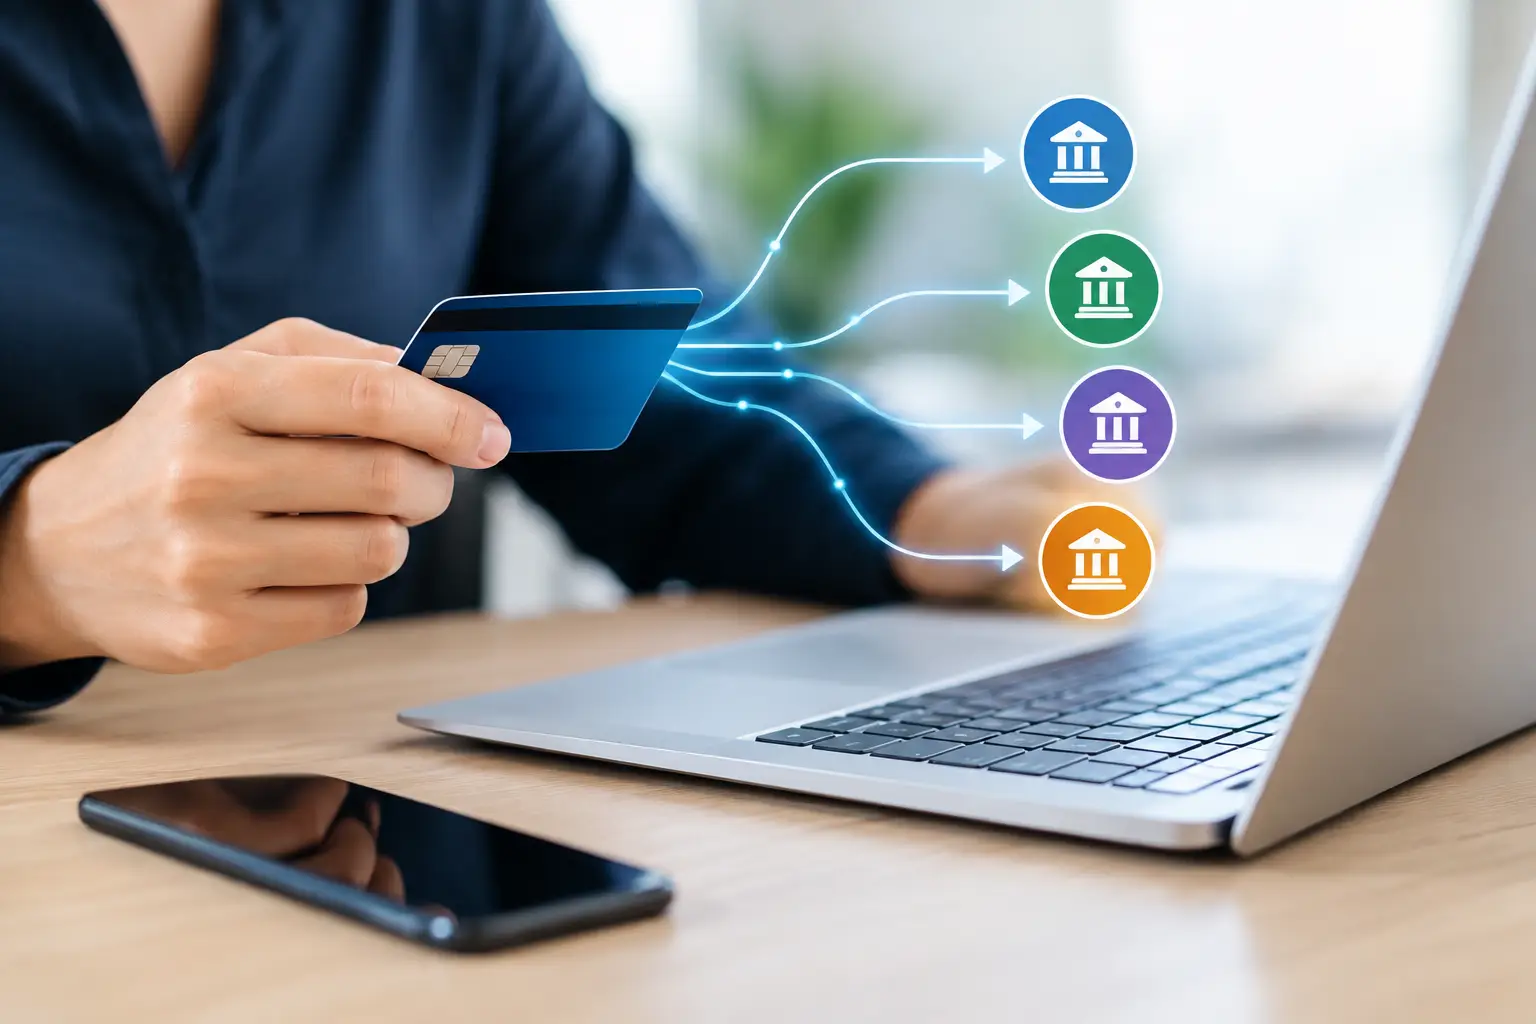
A card payment can fail before a customer has done anything wrong. The issuer may prefer a domestic acquiring route, reject a cross-border authorisation, or apply rules linked to the card’s product type. To route transactions by BIN is to use the card’s issuing information before authorisation, sending the payment through the acquiring path most likely to approve it at an acceptable cost and risk level.
For merchants operating across multiple markets, acquirers and payment service providers, this is not a minor technical setting. BIN-based routing can directly affect approval rates, checkout conversion, processing costs and the customer experience. It is especially valuable in sectors where issuer behaviour changes sharply by country, card scheme, recurring-payment profile or regulated merchant category.
What BIN routing means in practice
A Bank Identification Number, commonly called a BIN or Issuer Identification Number, is the opening sequence of a payment card number. It identifies key characteristics of the card, including the scheme, issuing bank, country of issue and, in many cases, whether the card is credit, debit, prepaid, commercial or consumer.
Historically, payment teams often worked with the first six digits. The industry’s move towards eight-digit BINs has made accurate BIN intelligence more important. Routing rules need current data and a platform capable of recognising the correct issuer range. A rule built around incomplete or outdated BIN information can send transactions down the wrong path and create the very friction it is meant to remove.
In an orchestration environment, the payment gateway reads the available BIN attributes and applies a defined routing policy. A French-issued Visa debit card, for example, may be sent to an acquirer with strong domestic issuer relationships in France. A commercial card from another region may follow a different route with more suitable pricing, acceptance capability or risk configuration.
The aim is not simply to find an acquirer that can process the card. It is to select the best available route for that transaction at that moment.
Why route transactions by BIN?
Issuer and acquirer relationships matter. Issuers often have different confidence levels, fraud controls and authorisation patterns for domestic and cross-border transactions. An acquirer with local reach, appropriate merchant category support and established scheme connectivity can produce a better authorisation outcome than a generic international route.
This matters most where volumes are substantial enough for small approval improvements to have commercial weight. A one or two percentage-point uplift in successful authorisations can represent meaningful retained revenue, particularly for subscription businesses, travel merchants, online gaming operators and high-frequency digital services.
BIN routing can also support cost control. Interchange, scheme fees and acquirer pricing vary by card type, geography and transaction profile. A merchant may choose one route for local consumer debit cards and another for international or commercial cards, provided the approach remains aligned with scheme rules, contractual obligations and customer outcomes.
There is also an operational benefit. Rather than relying on one acquirer to perform equally well across every territory, payment teams can use each partner for the markets and card segments where it is strongest. This reduces concentration risk without forcing customers through an unnecessarily complicated checkout.
Build routing rules around outcomes, not assumptions
The most effective BIN-routing strategy starts with payment data. Look beyond an acquirer’s overall approval rate. Aggregate figures can hide significant differences between issuing countries, card types, currencies, transaction values and merchant categories.
A useful analysis compares approval performance by BIN range or issuer, then assesses the primary acquirer against alternative available routes. If one route consistently performs better for UK-issued debit cards while another is stronger for cards issued in Germany or the Balkans, the evidence supports targeted routing rules.
However, a higher headline approval rate is not automatically the right answer. Consider the full transaction outcome: authorisation quality, fraud rate, chargebacks, processing cost, settlement currency, payout timing and customer support burden. A route that approves more transactions but generates avoidable fraud losses or high dispute rates is not a profitable route.
Start with clear routing conditions
BIN data is most useful when combined with other transaction signals. Typical conditions include card scheme, issuer country, card type, transaction currency, merchant entity, customer location, amount, recurring status and risk score.
For example, a merchant might route domestic cards to a local acquirer where local settlement and issuer familiarity are beneficial. Cross-border cards could be directed to an international acquirer with better coverage for that cardholder region. High-risk or unusually high-value transactions may require a route with stricter risk controls, stronger 3D Secure handling or a more suitable underwriting arrangement.
Rules should remain understandable. Overly granular logic can become difficult to maintain and may produce unexpected conflicts between conditions. Begin with the segments that represent meaningful volume or demonstrate a clear performance gap, then refine as data justifies it.
Use intelligent fallback, but do not retry blindly
Fallback routing is often paired with BIN logic. If the preferred acquirer returns a technical failure or a recoverable decline, the gateway may send the transaction to a secondary provider. This can protect revenue when an individual processor experiences an outage or has weaker performance for a specific issuer segment.
The distinction between technical and issuer declines is critical. Retrying a transaction after a hard decline, such as insufficient funds or a lost-card response, is unlikely to help and can create unnecessary issuer friction. Repeated authorisation attempts may also look suspicious and increase costs.
A sound retry policy uses response-code intelligence, timing controls and risk checks. It should define which decline types are eligible for fallback, how many attempts are permitted and whether the second route genuinely offers a different approval opportunity. For recurring payments, account updater services and network tokens may sometimes be more effective than another immediate retry.
Protect compliance, risk controls and customer trust
Routing decisions must not weaken authentication or fraud prevention. A transaction should still receive the correct 3D Secure v2 treatment, screening and monitoring for the chosen route. Where Strong Customer Authentication applies, routing must preserve the appropriate authentication flow and exemption logic.
Merchants should also avoid routing solely to bypass an acquirer’s risk appetite or a card scheme requirement. Acquiring partners need clear visibility of the business model, transaction profile and markets served. This is particularly important for regulated or high-risk verticals, where transparent underwriting and consistent controls protect long-term processing continuity.
From a data-security perspective, BIN routing should operate within a PCI DSS-compliant payment environment. Tokenised card data, hosted payment fields and properly scoped integrations reduce exposure while giving the routing engine the data it needs to make a decision. Payment teams should validate that their configuration supports eight-digit BIN recognition without storing or exposing unnecessary card data.
Measure the results after launch
Routing is not a set-and-forget feature. Issuer behaviour changes, acquirer performance moves, new BIN ranges appear and scheme rules evolve. Monitor results by issuer country, BIN segment, acquirer, currency, device type and payment model.
Approval rate remains a core metric, but it needs context. Track soft and hard declines separately, compare fraud and chargeback outcomes, and measure the cost per successful transaction. Watch customer-facing signals as well, including checkout abandonment, payment completion time and the share of payments requiring a second attempt.
A controlled test is often the best way to introduce a new routing rule. Send a limited, representative portion of eligible traffic to the proposed route and compare results against a baseline. Avoid judging performance too quickly: day-of-week patterns, marketing campaigns and issuer outages can distort a short test.
For merchants managing multiple PSPs and acquirers, a central orchestration layer makes this process practical. AllSecure can help businesses configure routing logic around real payment performance, while retaining the flexibility to adapt rules as markets, issuers and risk conditions change.
When BIN routing is not the answer
BIN data is powerful, but it cannot explain every decline. A customer may abandon because authentication is cumbersome, the payment page loads slowly, the preferred local payment method is missing or the transaction triggers legitimate fraud controls. In those cases, changing the acquirer route alone will not repair conversion.
BIN routing may also offer limited value for a merchant with a single market, one well-performing acquirer and modest transaction volume. The additional operational complexity has to earn its place. For these businesses, improving checkout design, 3D Secure performance or decline recovery may be the more immediate priority.
The strongest payment strategy treats BIN routing as one part of a wider optimisation programme. Match the right acquirer to the right transaction, keep risk and compliance controls intact, and review the evidence often enough to act before lost approvals become lost customers.
Related Articles